Cruise travel insurance is built for the problems that only happen at sea, like being stuck in your cabin with an illness, missing the ship at a port, or needing to be taken off the ship for treatment. A standard travel policy may cover some of your trip, but it can leave real gaps once you step on board.
If you're booking a cruise, it helps to know what's different and what to look for before you buy.
What Standard Travel Insurance Usually Covers on a Cruise
A standard policy is designed around land-based trips. Which? says standard travel cover isn't enough for a cruise, and that it won't cover the cost of a rescue from a cruise ship. Without specific cruise cover, you may not be protected for cruise-specific problems.
Some standard policies exclude cruises completely. Others include them but leave out the extras that make cruise cover useful. Check the policy wording rather than assuming a cruise is included.
Why Medical Cover Matters More at Sea
Ship Medical Centres Usually Charge
Medical centres on cruise ships are often privately run. Which?, in its guide to what to do if your cruise goes wrong, notes that medical charges are billed to your onboard account. Even a short illness can lead to a bill.
Your GHIC Won't Cover You On Board
A UK Global Health Insurance Card (GHIC) is useful in many countries, but it won't give you state provided medical care on board. The NHS Business Services Authority says it doesn't cover any treatment on a cruise ship, even if the ship is docked. You may be able to use it for state-provided treatment if you're taken to a public hospital on land in a country where it's accepted.
Getting Off the Ship Can Be Expensive
If you need hospital treatment at sea, you may have to be moved by tender boat or helicopter. That's harder and more costly than getting to hospital on land, which is why the medical and repatriation limits on a cruise policy matter so much.
The Cruise Extras to Look For
Cruise cover adds benefits you won't usually find on a standard policy. Names and limits vary, but these are the common ones.
Cabin Confinement
If the ship's doctor confines you to your cabin for medical reasons, this pays a set amount for each 24 hours you're stuck there, up to a maximum. It's there because you're paying for a holiday you can't use.
Missed Port Departure
If a covered delay stops you getting back to the ship at a port and it leaves without you, this can help with the cost of catching up with it at the next port. Check which delays count, because each policy sets its own list.
Itinerary Change or Missed Ports
Bad weather, technical problems or local issues can mean the ship skips a scheduled port. Some policies pay a fixed amount for each missed port.
Cruise Interruption
If you have to leave the cruise early, for example after being taken off for medical treatment, this can cover the part of your cruise you didn't get to use.
Unused Excursions
Shore trips are often booked and paid for in advance. If illness or a covered event means you can't go, this can refund pre-paid excursions up to a limit.
Missed Departure at the Start
Missing the ship at the start of your cruise, because of a delayed flight or transport problem, can be expensive. Some cruise policies cover the cost of getting to the next port to join the ship.
A Quick Example
Say you book a two-week Mediterranean cruise and fall ill on day three. The ship's doctor confines you to your cabin for two days, and you miss a shore excursion you'd already paid for.
A standard policy might help with the medical bill. The cabin confinement payment and the refund for the unused excursion would usually only come from cruise extras. That's the gap cruise cover is designed to fill.
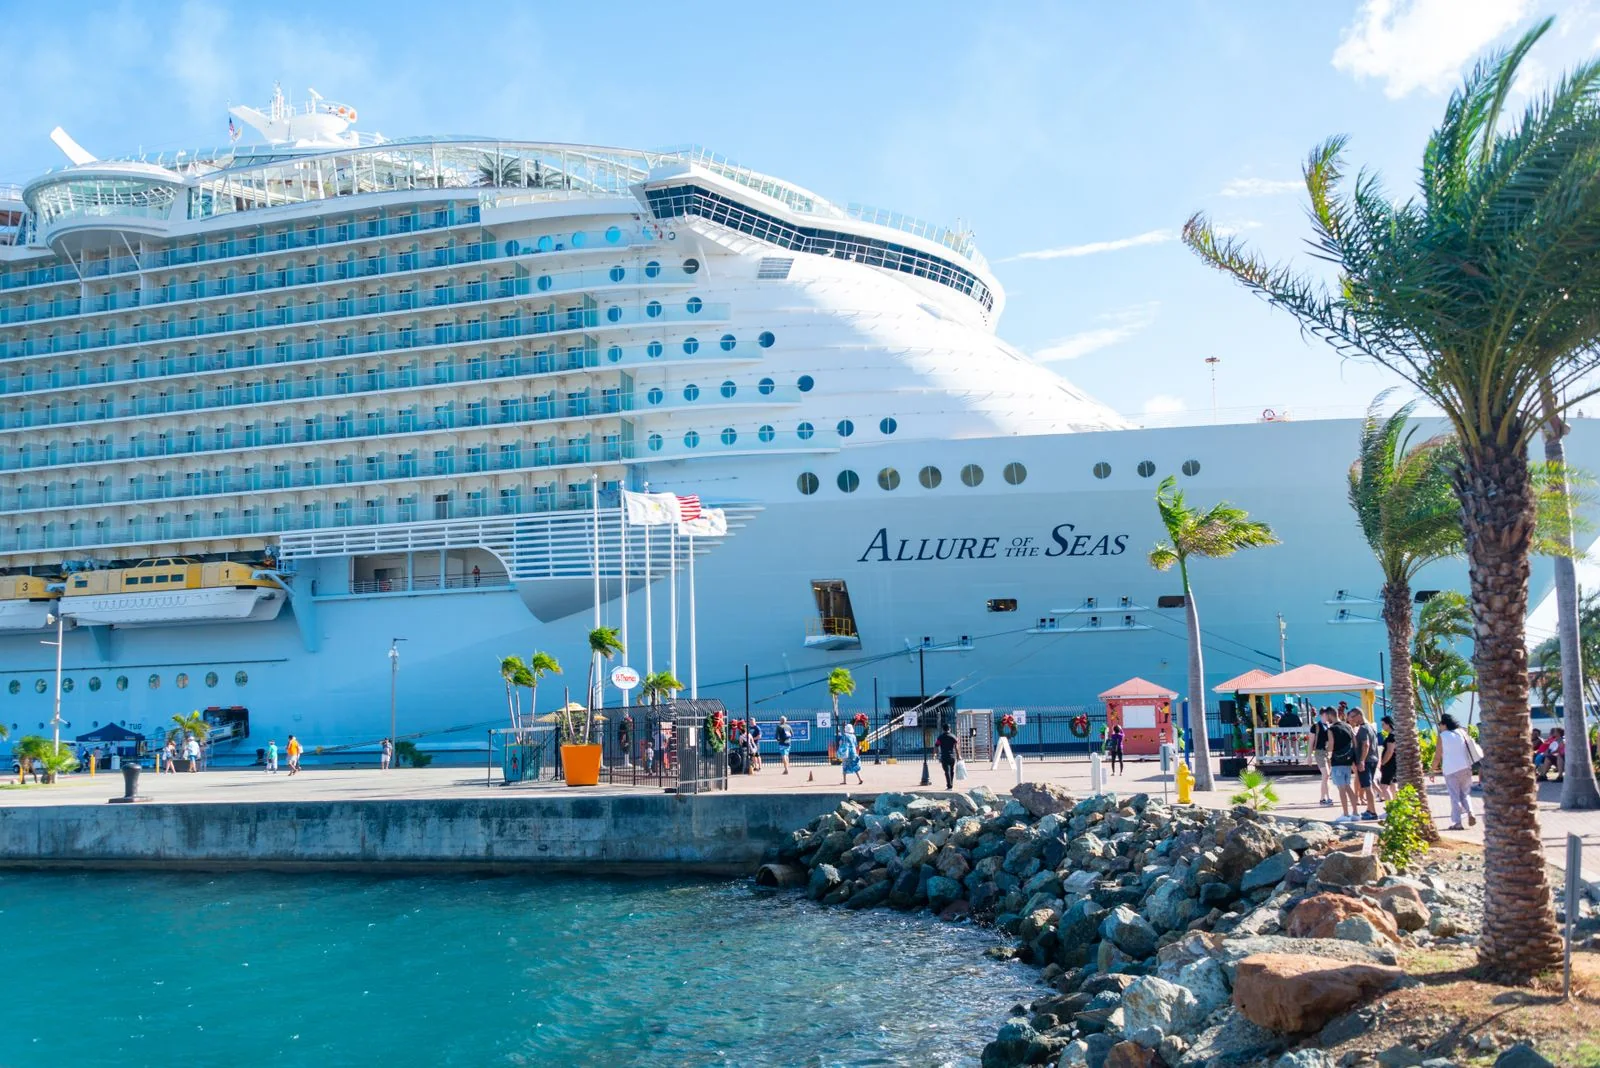
Ocean Cruises and River Cruises
River cruises can also require cruise-specific cover. If you're booking a trip along the Rhine or the Danube, check whether the insurer treats it as a cruise and whether cruise cover is included or must be added.
Picking the Right Region
Like other travel cover, cruise travel insurance is priced by region, and cruises can be tricky because a single itinerary can cross several areas. Check every port of call, not just where the ship sets off.
- A Mediterranean cruise may call at ports outside Europe as some insurers define it. Check how your insurer defines Europe.
- Caribbean cruises are often grouped with the USA, Canada and Mexico, which usually means the highest-priced worldwide region.
- If you fly to a departure port in the USA, your cover will need to include the USA.
Picking a region that doesn't match your full itinerary could leave you without cover in some ports.
When to Buy Cruise Travel Insurance
Cruises are often booked many months ahead, and deposits can be large. With a single-trip policy, cancellation cover usually starts from the moment you buy it. That's why many travellers arrange cover soon after booking rather than closer to departure.
If you fall ill or another covered event stops you travelling before you sail, the policy may help with cancellation costs. If you cruise every year, check both the price and the cover again at renewal.
Medical Conditions and Age on a Cruise
If you have any medical conditions, declare them all, including pending treatment or tests. Leaving one out could mean a claim is turned down, and that matters even more at sea, where treatment and evacuation can be costly.
Upper age limits vary between insurers, and some charge more as you get older. If you have health conditions, you may find specialist policies are a better match. Either way, answer the medical questions fully.
A condition left off the application could mean a claim is turned down. Give the same complete medical and trip details for every quote so you can compare the cover and price fairly.
Annual Policies and Cruises
If you take more than one trip a year, an annual policy might suit you, but don't assume it includes cruises. Which? has looked at why annual cover might not include a cruise holiday, and found that some annual policies only include cruise cover as a paid add-on, and some don't offer it at all. The per-trip day limit also matters for longer voyages, so check your cruise fits within it.
What to Check on Cruise Travel Insurance Before You Buy
Here's a quick checklist to run through:
- Does the policy include cruises, or do you need an add-on?
- Does your cruise line require specific cruise cover, and does this policy meet it?
- Is the region right for every port on your itinerary?
- What are the medical and repatriation limits, including evacuation from the ship?
- What do the cruise extras pay, and are there daily or total caps?
- Have you declared all medical conditions, including ones you think are minor?
- What's the excess, and does it apply per person or per claim? Check this on every quote because the excess can materially change what you receive from a claim.
Common Exclusions
Even good cruise policies have limits. Typical exclusions include:
- Undeclared pre-existing medical conditions
- Incidents linked to drinking too much alcohol
- Going against Foreign, Commonwealth and Development Office (FCDO) travel advice, which GOV.UK says could invalidate your insurance
- Activities on shore trips that need extra cover, such as some water sports
Reading the exclusions section takes a few minutes and can stop a nasty surprise later.
If you're booking time at sea, it's worth having cruise travel insurance in place before you sail, so you're covered for the problems a land-based policy was never designed to handle.
Frequently Asked Questions (FAQs)
1. Do I Need Special Insurance for a Cruise?
Often, yes. Standard policies may exclude cruises or only cover some costs, and Which? says standard travel cover isn't enough for a cruise. Check the policy includes cruise-specific benefits.
2. Does My GHIC Work on a Cruise Ship?
No. The NHS Business Services Authority says a GHIC doesn't cover treatment on board a cruise ship. It may help if you're taken to a state hospital on land in a country that accepts it.
3. What Is Cabin Confinement Cover?
It pays a set amount for each 24 hours the ship's doctor confines you to your cabin for medical reasons, up to a maximum limit.
4. Are River Cruises Covered by Cruise Insurance?
Many cruise policies include river cruises, but the definition and requirements vary. Check whether your insurer treats the trip as a cruise and whether cruise cover is included or must be added.
5. Does Annual Travel Insurance Include Cruises?
Not always. Some annual policies only include cruise cover as a paid add-on, and some don't offer it, and long voyages must still fit within the policy's per-trip day limit.